posted on August 4, 2026
Car leasing is often pitched as a more flexible alternative to purchasing a car. On the surface, lower monthly payments, a new car every few years, and no long-term commitment all sound like a good deal. But in reality, leasing a car comes with plenty of drawbacks from strict mileage limits to hefty wear-and-tear charges, along with early termination fees if you decide to break the lease period early.
That’s why many drivers are considering how to get a car without a lease. Below, discover five alternatives to a traditional leased vehicle, helping you weigh the pros, cons, and considerations to make an informed choice before you sign a lease.
In this guide, we’ll be covering:
- Why people lease cars
- 5 alternatives to getting a car (without traditional leasing):
- Option 1: Renting a car
- Option 2: Buying a car outright (new or used)
- Option 3: Financing a car purchase
- Option 4: Subscription car services
- Option 5: Going car-free or car-light
- How to decide which option is right for you
- Frequently asked questions
Why people lease cars
The appeal of a car lease goes beyond that new car smell. Leasing is pitched as a flexible alternative to car ownership, with lower monthly car payments than a financed vehicle, the ability to always drive something new, and no need to worry about the car’s potential resale value. For drivers who want a new car every couple of years and drive modest mileage, leasing can have real advantages.
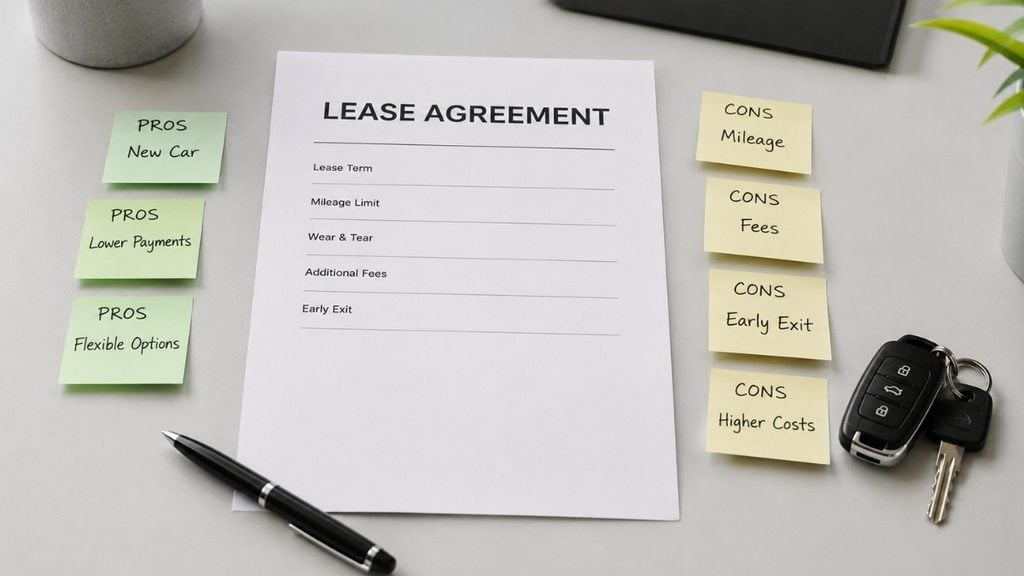
But there are hidden fees and drawbacks that many drivers don’t account for when leasing a car. Leased cars usually have a mileage limit (meaning you can only drive around 10,000 to 15,000 miles per year without being charged extra fees). There are also wear-and-tear charges that are payable at the end of the lease, disposition fees when you return the car, along with high fees if you want to terminate the lease early.
Over time, leasing can be more expensive than buying a car (even if it’s financed). At the end of the lease, you walk away with nothing, whereas repaying a car loan means you’ll reach a point where the car is paid off and an asset you own. If you’re planning to own a car for 5-10 years or more, buying almost always wins financially.
5 alternatives to getting a car (without traditional leasing)
While car leasing gives you access to a brand new vehicle, there are ways to access the same car (or a similar model) without the high fees, rigid contracts, and strict mileage limits. Here are five alternatives to consider.
Option 1: Rent a car
- Best for: Occasional drivers, transitional periods, or anyone wanting to test a car before committing to a purchase.
- Key advantage over leasing: No long-term contract and greater flexibility; book by the day, week, or month and walk away when you’re done.
- Key consideration: Costs more per day than ownership if you need a car constantly.
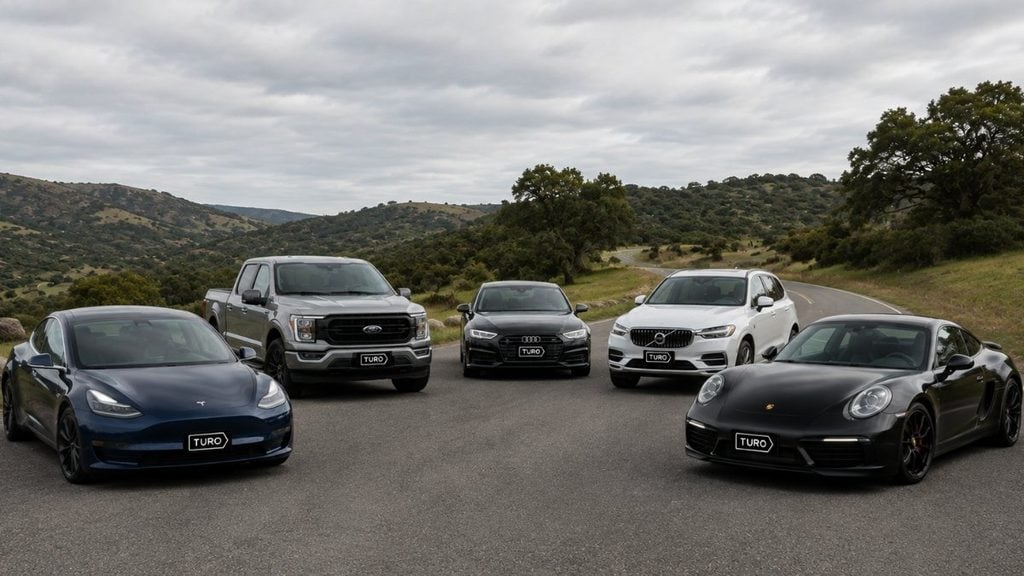
Not sure exactly what car you want to drive or how long you’ll need it? Renting a car on Turo is the most flexible way to access a car (without locking yourself into a rigid lease). On Turo, you can rent cars for the day, the week, or even multiple months, with the ability to filter by newer makes and models.
If you only need a car occasionally, are in the midst of a life change (such as relocating for work or in between car leases), or want maximum flexibility without the weight of car ownership, renting on Turo is a perfect fit. Browse by cars available near you, compare hundreds of unique makes and models, and book for exactly as long as you need (with many vehicles available for delivery directly to your hotel, office, or home address).
Unlike traditional car rental companies, booking on Turo means the exact car you rent is the car you’ll drive. Read reviews from past drivers and access a wide range of vehicles you won’t find in a traditional rental company fleet (from the latest EV models to sleek SUVs and luxury cars). On Turo, there’s no down payment, no early termination fees, and no lock-in contract. You can even request to extend your booking during your trip if plans change.
Tip from the author: Planning to rent a car for multiple weeks or months? Many vehicle listings on Turo offer discounts for longer bookings, allowing you to save and reduce the costs of renting a car (making this one of the most affordable alternatives to traditional car leasing).
Option 2: Buy a car outright
- Best for: Buyers with available capital who want the lowest total cost and maximum flexibility.
- Key advantage over leasing: Full ownership from day one, with no mileage limits, no wear-and-tear fees, and no monthly repayments.
- Key consideration: Requires significant upfront capital; works best when buying a used or second-hand car to reduce the total sum required.
Want to skip lease terms altogether? If you have the cash available to cover the purchase price, buying a car outright is a viable alternative to car leasing. In fact, buying a car outright is the simplest way to access a car, but comes with a hefty upfront investment.
Buying a car means no monthly repayments, no interest charges, and no debt or car loan hanging over your head. You own the car from day one, can sell it whenever you want, and have no restrictions on things like mileage or modifications.
The biggest consideration is ensuring you have the capital ready to purchase the car outright. Buying a used vehicle is a smart way to reduce the purchase price, while new cars tend to come at a higher upfront cost.
Option 3: Finance a car purchase
- Best for: Drivers who want to build equity but can’t pay cash upfront
- Key advantage over leasing: Every payment builds toward ownership, meaning once the loan is paid off, you own an asset instead of nothing.
- Key consideration: Interest adds to total cost, and longer loan terms increase the risk of owing more than the car is worth.
Want to work towards owning a car without making a big upfront investment? Financing a car purchase is another alternative to car leasing, with auto loans allowing you to spread out the cost of the vehicle over several months (usually 24 to 72 months).
A big benefit of car financing is that you’re building equity with every payment. When the car loan is paid off, you own the vehicle. While a car purchase from a finance company costs more than paying outright in cash (due to the interest charges on the loan), you drive away with an asset you own at the end of the loan.
One factor to consider is the interest rate of your car loan. The difference between a 4% and 8% annual percentage rate (APR) on a $30,000 loan can be significant, particularly over a long finance term. By keeping your loan term under 60 months, you can keep interest costs down and reduce the number of payments required.
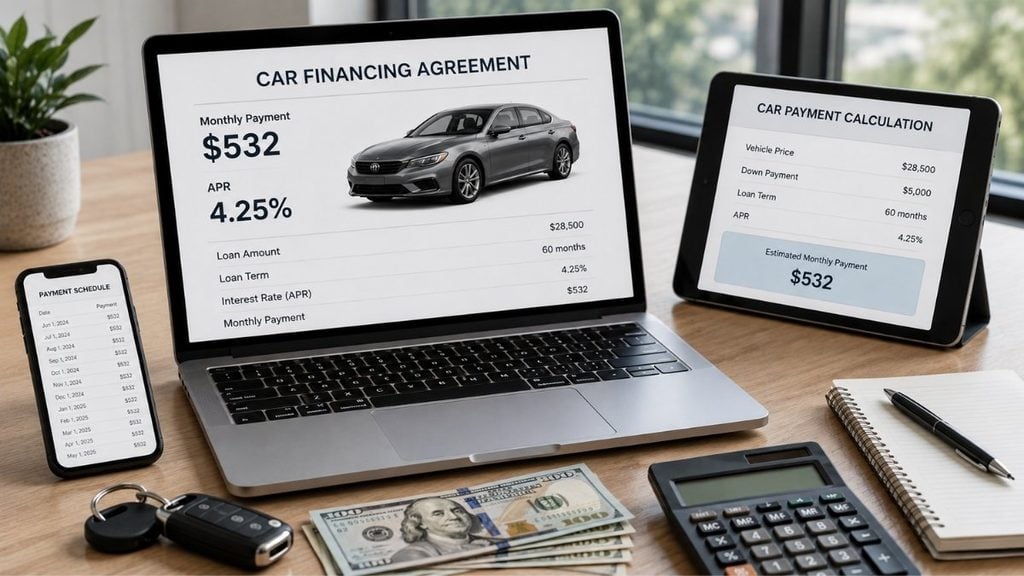
Tip from the author: Compare the total cost of financing vs. leasing the same vehicle over the same period, not just the monthly payment. Monthly lease payments are lower, but over 3–4 years the total amount paid, plus the fact you own nothing at the end, often makes financing the better financial decision.
Option 4: Car subscription services
- Best for: Short-to-medium-term car access where maximum flexibility justifies a premium price.
- Key advantage over leasing: Month-to-month flexibility with insurance and maintenance bundled in, with an arrangement that’s easier to cancel than a lease.
- Key consideration: More expensive per month than leasing or financing for the same vehicle; market availability varies by region.
Car subscription services allow you to pay a monthly fee to access a vehicle (sometimes with the option to swap between a fleet of cars) with insurance, maintenance, and registration included in a single monthly payment.
Car subscriptions tend to be more flexible than a car lease agreement, running month-to-month with the ability to cancel along the way. The catch is that subscription payments tend to be more expensive compared to a loan or lease payment.
While car subscriptions offer high convenience and flexibility, you do pay a premium for it. If you only need short-term access to a car and don’t want the hassle or paperwork of leasing or buying, this can be a good alternative. However, if you’re going to be using a car long-term, the monthly cost can be hard to justify.
Option 5: Go car-free or car-light
- Best for: Drivers in dense, walkable areas with strong public transportation and rideshare coverage.
- Key advantage over leasing: Lowest possible ongoing cost, with no monthly payment and no vehicle-related expenses at all.
- Key consideration: Impractical in most suburban or rural areas; occasional needs still require an on-demand car rental.
If you only need a car occasionally, it might be worth going without a car altogether. In walkable cities with strong public transportation networks, you might be able to get around without your own vehicle. The monthly costs of using a public transportation pass, cycling, and the occasional rideshare are usually a fraction of the cost of car ownership or leasing.
But this alternative isn’t feasible for everyone. If you live in a suburban or remote area without access to rideshares or public transit, going without a car isn’t a realistic option.
For those who need a car occasionally, renting a car for the day or the weekend bridges the gap without any fixed monthly commitment.
How to decide which option is right for you
From owning a car outright to securing a lease or renting a car on Turo, the right option depends on your driving habits, location, and mileage needs. Use these questions to assess your current situation:
- How many miles do you drive per year?
- Do you need a car every day, or just occasionally?
- How long do you plan to use the same vehicle?
- How stable is your financial and living situation?
With these answers in mind, here’s a helpful framework to help guide your decision:
- If you drive frequently and want to build equity over time: Buying (outright or financed) is almost certainly the better long-term financial choice.
- If you drive moderate mileage and want a new car every 2–3 years: Leasing has genuine advantages, but compare the total costs to leasing over 5–6 years, not just the monthly payment.
- If you need a car occasionally or are in a transitional period: Renting a car through Turo or a car subscription offers access to your own vehicle without commitment.
- If you live in a walkable city with reliable transit: Going car-free is worth serious consideration, paired with rideshares or renting a car on Turo when you need it.
Frequently asked questions about getting a car without a lease
Is leasing a car worth it?
For a specific type of driver (someone who wants a new car every 2–3 years, drives modest mileage, and values lower monthly payments over building equity), leasing has some advantages. For most drivers over a 5–10 year horizon, buying (either outright or financed) is significantly less expensive in total, because lease payments build toward nothing. Run the total cost comparison for your specific situation rather than comparing monthly payments alone.
What happens if I don’t want to lease but can’t afford to buy outright?
Financing a car purchase is the most common middle path; auto loans spread the purchase cost over 24–72 months while you build equity with each payment. Used cars reduce the required loan amount significantly and often offer better value than leasing a new car at a similar monthly payment. For those in a transitional period, renting through Turo provides car access without any long-term financial commitment.
Is it cheaper to lease or finance a car?
Monthly lease payments are typically lower than loan payments for the same vehicle, but this side-by-side comparison can be misleading. At the end of a loan, you own the car outright. At the end of a lease, you own nothing and face another payment decision. Over a 6–10 year period, financing a car and keeping it until it’s paid off is almost always less expensive in total than a sequence of leases for the same vehicle.
What are the downsides of leasing a car?
Leases come with mileage limits (typically 10,000–15,000 miles per year, and have expensive fees if you exceed these limits), wear-and-tear charges at return, early termination fees if your circumstances change, disposition fees when you hand the car back, and no equity built toward ownership. The monthly payment is lower, but you’re essentially renting a depreciating asset indefinitely.
Can I rent a car long-term instead of leasing on Turo?
Yes. On Turo, you can find cars available to rent for weeks or months, with many offering discounted rates for longer bookings. This is a flexible alternative to a short-term lease for people who need a car for a defined period without a long-term financial commitment.
How much does it cost to get out of a lease early?
Early lease termination is typically expensive; costs vary but often include remaining monthly payments, early termination fees, and any gap between the car’s current value and what you owe. Most lease agreements lock you in financially for the entire term. This is one of the key arguments against leasing for people whose circumstances might change: a loan can be paid off early with minimal penalty, but breaking a lease is expensive. If you’re considering leasing and there’s any uncertainty about your situation in the next two to three years, a purchase or rental arrangement offers significantly more flexibility.
Get the car access you need, on your terms
Getting a car doesn’t have to mean signing a lease. Whether you buy outright, finance a used vehicle, or rent through Turo, there are plenty of alternatives that give you access to a car on terms that work for your life rather than a leasing company’s contract.
For flexible car access without the commitment of a lease, browse Turo for a wide range of vehicles with booking lengths from a single day to several months.
Share your car, earn extra cash
Cover your car payments or earn some extra cash by sharing your car whenever you’re not using it.
Get startedHit the road
Browse thousands of cars for every occasion and budget near you, or wherever you’re going.
Browse cars
Lucinda Starr
Lucinda Starr is a travel and automotive writer with 5+ years of firsthand experience road-tripping across Australia, New Zealand, and beyond. She writes road trip guides for Turo, drawing on her experience behind the wheel to share practical insights on long-distance drives, destinations, and vehicles. Her travels have taken her across Australia’s East Coast, Victoria’s Great Ocean Road, the Northern Rivers, Byron Bay, and both islands of New Zealand. One of her most memorable journeys was an 11-day, 2,600+ km route from Auckland to Punakaiki and Queenstown. Lucinda has a particular passion for classic, rugged 4WD vehicles and the freedom they bring to exploring new places.